01 Public project · AlgoTrading
Strategy research & paper trading
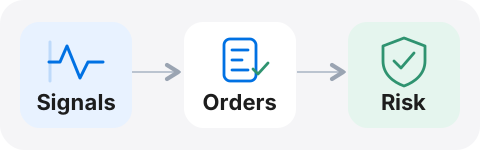
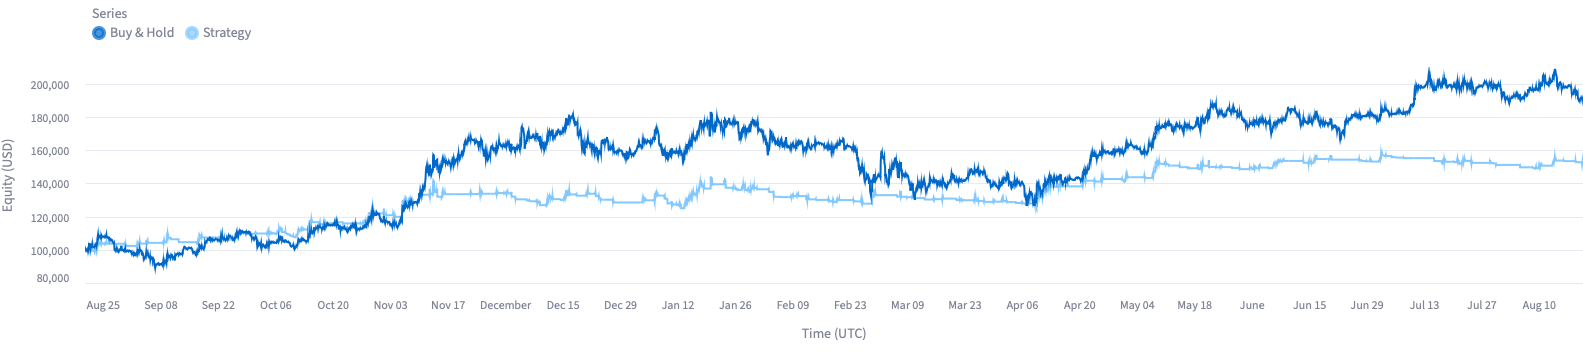
Tracked strategies from backtests through paper trades. I connected Alpaca order execution, data checks, and risk monitoring, with saved results and a dashboard for review.
Hi, I’m Kecheng. I completed my master’s in Mathematics of Finance at Columbia, where I was a teaching assistant for Machine Learning for Finance. I’m based in New York and enjoy connecting mathematical ideas with the software needed to test them.
I’m interested in quantitative research roles where I can take an idea from the mathematics through the code and into a careful test. I’m curious, comfortable questioning my first answer, and serious about making the reasoning clear. My 2300 blitz chess rating is a clue to my competitive side, too.
The projects below show how I think through data, models, and risk. The background section adds the places, languages, and interests that shape me.
You can support my work through PayPal, Venmo, Zelle, or Apple Cash. Scan or select a QR code, or copy the phone number below.
1 / 4 projects
01 Public project · AlgoTrading
Tracked strategies from backtests through paper trades. I connected Alpaca order execution, data checks, and risk monitoring, with saved results and a dashboard for review.
02 Numeraxial · Professional research
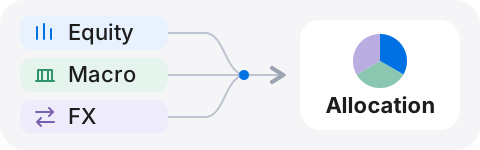
Made portfolio comparisons repeatable with consistent market data. At Numeraxial, I standardized Bloomberg inputs and built reusable workflows to compare allocations, turnover, and downside risk.
03 Columbia · Academic project
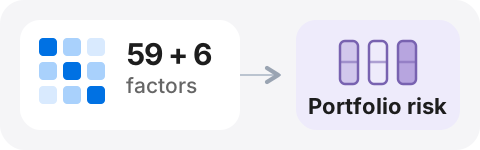
Evaluated portfolio returns alongside total and stock-specific risk. I compared regression and neural-network models using 59 industry and six style factors, then calculated portfolio weights.
04 CQF · Academic study
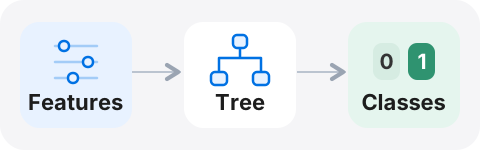
Compared feature selection and tuning methods for classifying SPY returns. I built an XGBoost workflow with saved evaluation results. Its same-day return target limits its use for forecasting.
Standardized market data and built reusable research tools to compare market regimes and portfolio allocations under constraints. Project details
Tested EMA–ADX and Z-score cryptocurrency strategies, evaluating parameter sensitivity, trading costs, turnover, value at risk (VaR), and drawdowns.
Teaching assistant · Machine Learning for Finance (MATH GR5430)
Machine Learning, Time Series Modeling, Stochastic Process, Programming for Computational Finance, Numerical Methods, Derivatives Trading, Option Pricing.
GPA: 3.83/4.0 · First-class honours (WES report)
Stochastic Theory, Linear Statistical Models, Mathematical Risk Theory, Applied Probability, Derivative Securities, Numerical Methods, Operational Research, Statistics and Probability, Financial Reporting.
I studied Mathematics of Finance at Columbia and now work on quantitative research at Numeraxial.
I completed my B.Sc. in Mathematics with Finance at the University of Liverpool.
I studied in Suzhou and worked as a quantitative analyst intern at Western Securities in Shanghai.